Market Matching
We define the right business for you based on your capital, experience, and goals. Together, we establish clear acquisition criteria so every opportunity fits the ownership role and lifestyle you want.
For aspiring entrepreneurs and business owners with $100K+ in available capital
We handle sourcing, due diligence, financing, and negotiations so you can buy your first business or grow the one you already own.
We define the right business for you based on your capital, experience, and goals. Together, we establish clear acquisition criteria so every opportunity fits the ownership role and lifestyle you want.
We research the market, contact business owners, and screen opportunities against your criteria. Our team handles the outreach and follow-up so you can focus on evaluating qualified businesses.
We analyze the financials, assess operational risks, and determine what the business is worth. We then structure and negotiate an offer designed to protect your interests.
We coordinate deeper due diligence, financing, and the legal closing process. Our team works with lenders, attorneys, and the seller to resolve issues and move the acquisition through to completion.
We help coordinate the seller handover, clarify operating responsibilities, and establish your priorities as the new owner. Where needed, we also support management placement to help the business operate without depending on you day to day.
 Kevin
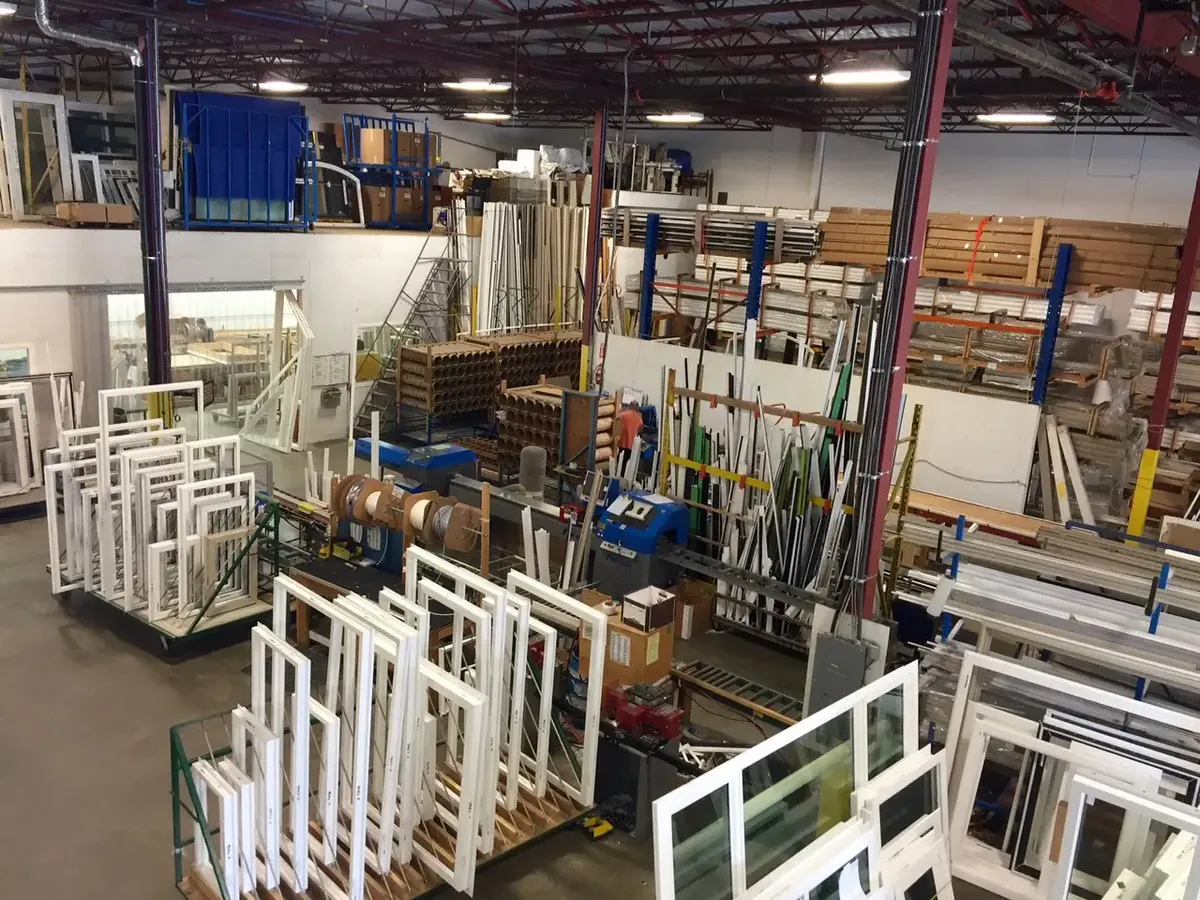
After a construction injury, Kevin acquired a business with installation crews already in place. He closed in roughly four months, at approximately $80K below the seller’s asking price.
 Private Equity Firm
We sourced an off-market software business generating $2.2M in annual EBITDA for a private equity buyer. The completed acquisition came with a pipeline of four more targets under letters of intent.
 Laurie
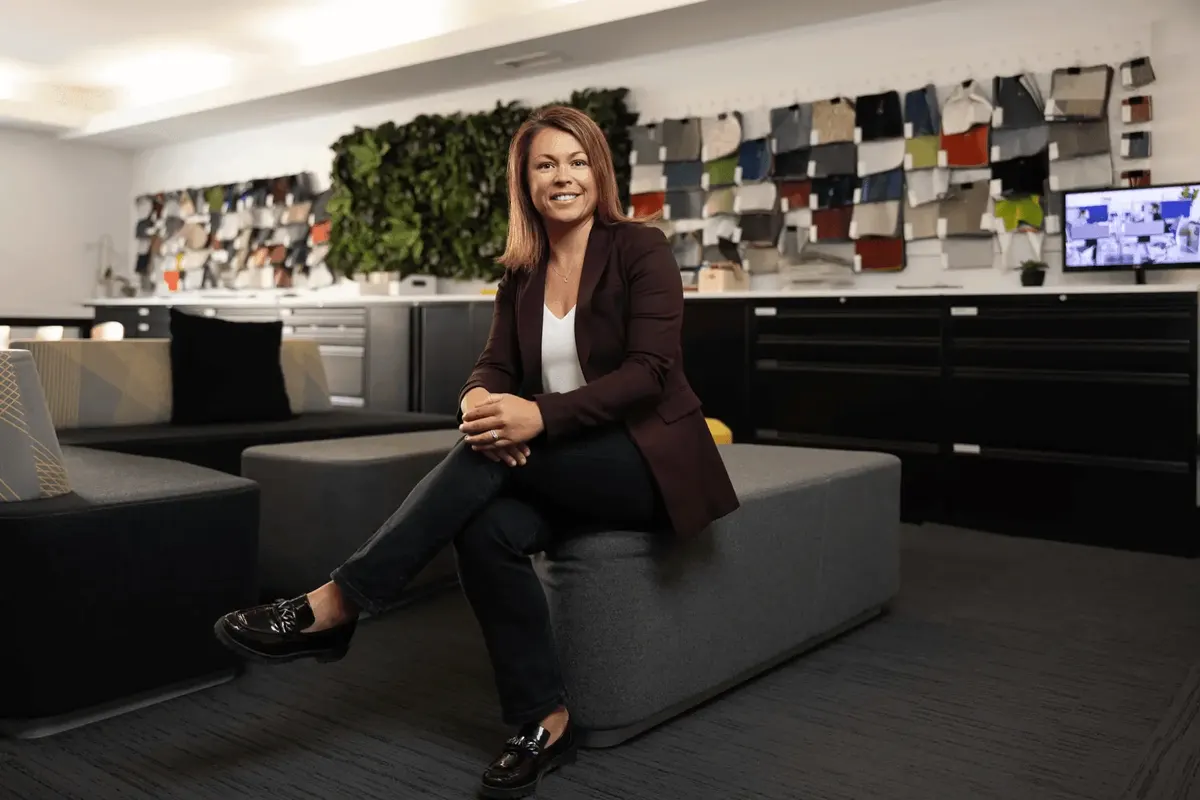
, a marketing executive, acquired a countertop manufacturer generating her more than $500K in first-year net income. Our diligence also uncovered $1.7M in under-reported stone inventory.
 Annique
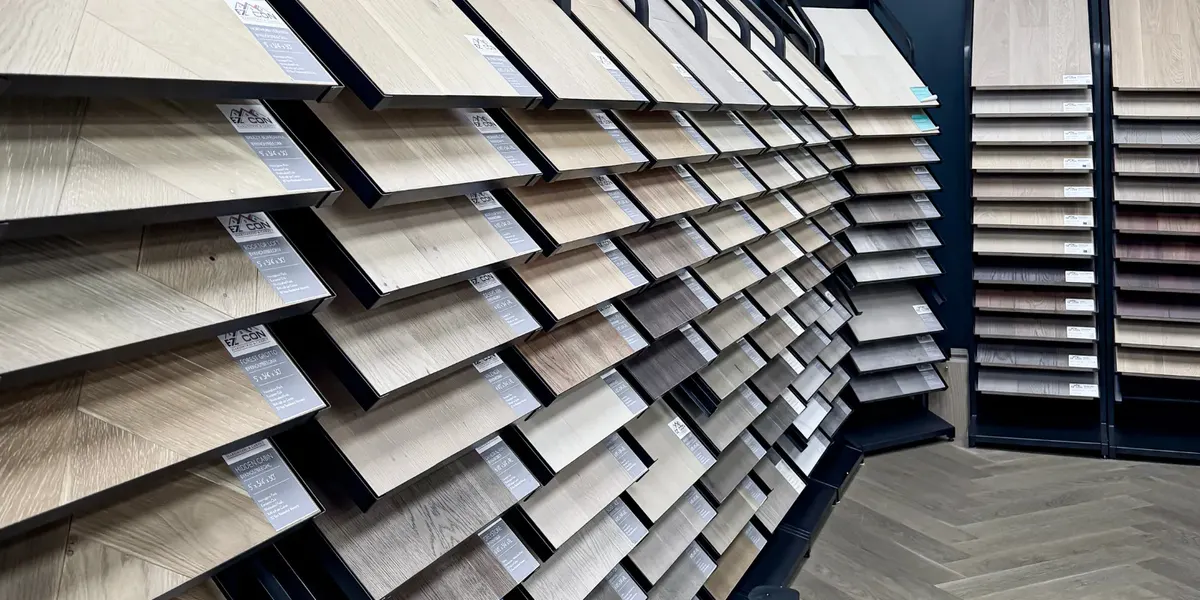
 left a $60K job to acquire a flooring business with $40K of her own money. In year one, cash flow after debt payments exceeded her entire initial investment, on top of her salary.
 Eric
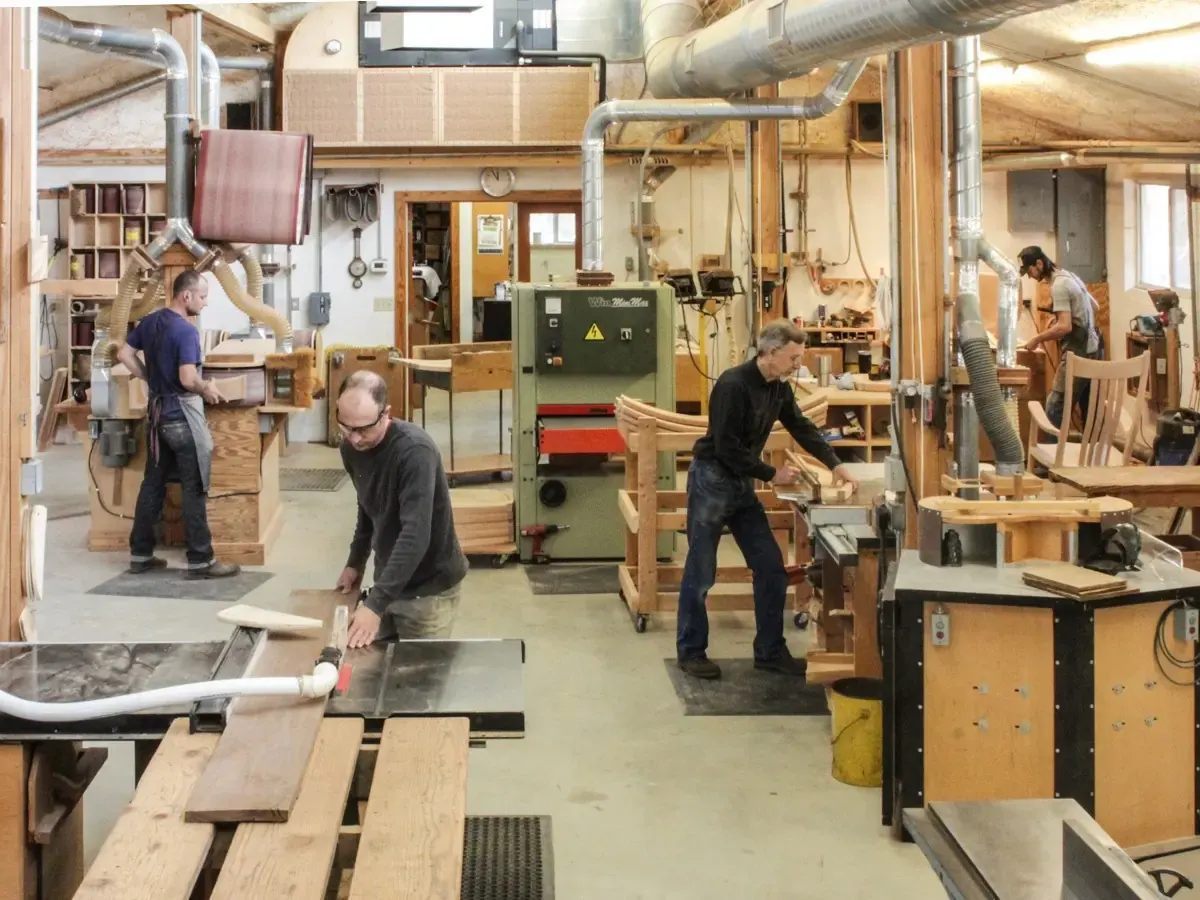
Eric acquired the building and an existing production team. With capacity to take on more work and no online presence, he plans to grow demand through new advertising channels.
I’ve been working with the GuildShore team for about eight months and I couldn’t recommend them more highly.
Every team member we’ve had the pleasure of interacting with has been knowledgeable, professional and sincerely invested in our success.
As first-time business buyers, the acquisition process could feel complex and intimidating. However, the team guided us through every step with exceptional professionalism.
Their expertise, availability and strategic advice gave us the confidence to move forward and played a decisive role in completing our first acquisition.
If you’re looking for a team that thoroughly understands business acquisitions and proactively supports you throughout the process, I recommend GuildShore without hesitation.
A huge thank-you to the entire team for your exceptional support!
From the beginning, the GuildShore team was very responsive and attentive to our needs. They suggested several very interesting ideas and the opportunity we ultimately pursued was in an industry neither my wife nor I had considered entering (but we’re delighted we did).
It’s now been three months since we completed the acquisition and we couldn’t be happier. Every morning, we wake up motivated and full of energy to tackle the challenges of our business.
We’re already starting to think about the next opportunity and look forward to working with GuildShore again.
We highly recommend them to anyone looking for support throughout the business acquisition process.
An excellent advisory firm for business buyers. I’m currently working with Elizabeth and Alican, who are both essential to the success of my project. They’re two dedicated, organized, and energetic people who manage my acquisition thoroughly and proactively.
I feel well supported and highly recommend GuildShore!
I really appreciated the professionalism and accountability between the buyer and seller.
Made the entire process so much easier for a first-time acquirer.
Will definitely come back for further acquisitions.
I loved my experience with the entire Guildshore team and their process!
I recommend their support 100%!
I just completed a transaction in which they supported the buyers throughout the process.
Everything went very well.
What I like about GuildShore is the support. My advisor, Claude, guides me through the steps involved in the acquisition process.
After each step, we review it during our follow-up meeting and prepare for the next one so we can continue in a thorough and disciplined way.
Great support over the past several months! I’ve been introduced to several off-market businesses, and I’ve really felt things pick up since I started working with Amina. Truly excellent follow-up and guidance Thank you, Amina, and the entire GuildShore team
Excellent explanations that make the terminology easy to understand, and excellent service. I recommend them! Thank you!
Gabriel and the GuildShore team played a decisive role in the success of our acquisition. I especially want to recognize Gabriel’s contribution: his availability, expertise, and guidance throughout the process made all the difference. A team you can truly count on. I recommend them without reservation.
An excellent firm to support you with your business acquisition project.
I highly recommend their services because of their professionalism and good faith when problems arise. They were very generous and understanding during a situation that was particularly delicate and stressful for me. Don’t hesitate to call them!
Every week, our team sources, analyzes, negotiates, and structures acquisitions on behalf of our clients.
Below is a snapshot of transactions currently moving through financing, diligence and closing.
We run the entire buy-side desk.
Thesis definition. Direct outreach to off-market owners in your target vertical and geography. Broker network activation. A full seller snapshot on every live target within 48 hours, including normalized EBITDA, red flags and debt service coverage at the proposed structure. Lender pre-alignment before the first LOI. LOI drafting and negotiation, including seller notes and earnouts. Diligence coordination. Closing support and a 90 day handoff plan.
Thesis, branding and outreach locked in 2 weeks. First qualified targets in front of you inside 30 days. Signed LOI within 180 days, guaranteed. Close is typically 30 to 60 days after LOI depending on financing and diligence. Most clients own a business within 9 to 12 months of signing.
For comparison, the typical self-funded search takes 18 to 24 months and most searchers never close.
Plan on 2 to 5 hours per week for calls, reviewing opportunities, and making key decisions. You never source, screen or chase brokers.
That is the part that consumes searchers for a year, and it is the part we remove.
If we don’t get you a qualified business under LOI in 6 months, you get a full refund and continue working with you until you acquire a business.
Terms and conditions do apply, we'll walk you through how to qualify on our meeting.
Yes. Many of the buyers we work with are acquiring their first business.
We also work with existing business owners looking to acquire competitors, enter new markets, or add complementary businesses.
The important part isn't having acquisition experience. It's having the capital, commitment, and ability to operate or oversee the business you eventually buy.
Then we may have just saved you from buying the wrong business. We're not paid to convince you every opportunity is a good one. We're there to help you understand what you're actually buying before you own it.
We work on a success-fee basis, with a five-figure commitment upfront that is credited toward our fee when you acquire.
Exact terms vary depending on the size and complexity of the mandate, and how much of the acquisition process you want our team to handle.
If you're looking for a low-cost course, coaching program, or database subscription, we're probably not the right fit.
$5.4M Revenue · $1.1M EBITDA · ~4.4x Multiple
A first-time acquirer with a technical and corporate operating background is pursuing an established calibration and measurement-services company.
The buyer wants a business where technical capability and customer retention matter more than consumer branding.
An existing lab provides trained personnel, certifications, procedures, equipment, and customer relationships that would be difficult and time-consuming to recreate independently.
The company is being evaluated at approximately $4.8M, against roughly $1.1M in EBITDA.
Diligence centers on accreditation, technician retention, customer concentration, equipment requirements, recurring calibration schedules, and the transferability of key customer relationships.
Many customers need instruments recalibrated on recurring schedules to maintain quality standards and regulatory compliance.
That creates repeat demand without requiring the company to resell the customer from zero every year.
The buyer is effectively acquiring an installed base of future calibration events together with the technical infrastructure required to service them.
The buyer would inherit the laboratory, technicians, procedures, customer relationships, and recurring service schedule.
The opportunity is to improve utilization, expand customer penetration, and add adjacent calibration capabilities around an operating platform that already works.
Existing Plumbing Platform · $750K to $1.5M EBITDA Target · Strategic Service Expansion
A regional plumbing and drain-services company operating across the Carolinas and Georgia is pursuing the acquisition of an established septic operator to expand into an adjacent service line and increase revenue from the same residential and light-commercial customer base.
The buyer already operates a profitable home-services platform with technicians, dispatch, call handling, marketing, and field-service management in place.
Rather than build a septic division organically, recruit a specialized team, purchase trucks and equipment, and spend years building route density, the company is looking to acquire those capabilities through an existing operator.
The search is focused on septic companies valued between $4M and $6M, ideally generating $750K to $1.5M in EBITDA.
Priority targets have established pumping routes, trained technicians, a well-maintained fleet, strong local reputation, and revenue across pumping, inspections, repairs, and system replacement.
The target needs to work as a standalone acquisition, but the larger question is how much more valuable it becomes inside the buyer’s existing platform.
The two businesses already serve many of the same homeowners and property managers.
The plumbing company contributes customer acquisition, dispatch, marketing, recruiting, and back-office infrastructure. The septic company contributes specialized technicians, equipment, customer relationships, and recurring service routes.
That creates an opportunity to increase revenue per customer while spreading overhead across a broader service platform.
The buyer is not acquiring diversification for its own sake. It is acquiring a capability that fits directly into an existing operating system.
The septic business would continue operating as a specialized service line while gradually integrating into the buyer’s broader platform.
Marketing, scheduling, finance, recruiting, and customer service can be shared, while the acquired field team remains focused on septic work.
The end result is a broader regional home-services platform with more services per customer and another vertical that can support future bolt-on acquisitions.
Existing Platform: ~$6M Revenue · Target: $500K to $1.5M EBITDA per acquisition
A founder-led holdco already owns a profitable managed IT services company in the Southeast and is looking to grow the platform through acquisitions in adjacent markets.
The holdco already operates one MSP with an established technical team, recurring managed-service contracts, and centralized sales and administration.
The objective is not to enter a new industry. It is to acquire smaller MSPs that can be integrated into an operating platform that already understands service delivery, technician management, cybersecurity, and recurring IT contracts.
The search is focused on founder-owned MSPs in markets such as Charlotte, Raleigh, Atlanta, and Nashville, typically generating $500K to $1.5M in EBITDA.
Priority targets have a high percentage of recurring revenue, sticky SMB clients, a capable technical team, and limited dependence on the selling owner.
The buyer can acquire recurring revenue and customer relationships without rebuilding the technical infrastructure each time.
Billing, cybersecurity tools, help desk, procurement, finance, and management can increasingly be centralized across the group.
That means a bolt-on can potentially be worth more inside the existing platform than it is as a standalone owner-operated MSP.
The acquired company keeps its client relationships and technical staff while more of the back office moves onto the holdco’s existing infrastructure.
The holdco grows by adding revenue, technicians, and geographic density without recreating the operating system for every new location.
$500K Buyer Equity · Recurring Management Revenue · Florida Residential Portfolio
A successful real estate investor is pursuing the acquisition of an established residential property management company in Florida to add recurring operating income alongside an existing real estate portfolio.
The buyer already understands property ownership, tenant economics, maintenance coordination, and the operational demands of residential real estate.
The acquisition thesis is not based on learning a new sector. It is based on owning the service layer around an asset class the buyer already knows well.
With approximately $500K available for the acquisition, the search is focused on businesses in the $3M to $5M enterprise value range across major Florida markets, with enough management depth to operate without the seller remaining central to day-to-day decisions.
Priority targets have recurring management fees, a diversified landlord base, established property managers, and limited reliance on one large client or owner relationship.
The underwriting focuses on properties under management, revenue retention, fee structure, customer concentration, employee coverage, and normalized cash flow after replacing the seller’s responsibilities.
The objective is to combine buyer equity with acquisition financing and seller participation where appropriate, while preserving enough liquidity for the business after closing.
Property management offers a different path to scale than buying additional real estate directly.
The buyer can acquire a large base of recurring management revenue without deploying the amount of equity that would be required to own the underlying properties represented by those units.
Florida also offers a broad base of rental housing, investor-owned properties, and fragmented local operators, making the quality and density of the managed portfolio especially important when evaluating targets.
The buyer would move from owning individual properties to controlling a business that manages real estate at scale.
The focus becomes client retention, manager productivity, portfolio growth, service quality, and selective expansion into adjacent Florida markets rather than personally managing every property.
$3.7M Revenue · $280K EBITDA · 3.9x Multiple · $125K Buyer Equity
A buyer is pursuing an established childcare operation with significant existing revenue and an operating team already in place.
The buyer is approaching the opportunity as an operator and capital allocator rather than as the frontline service provider.
That matters because the acquisition thesis depends on managing an existing organization effectively, not replacing the people delivering the service.
The proposed $1.1M transaction includes approximately $125K in buyer equity, with the balance coming from external financing and seller participation.
The structure is designed to preserve buyer capital while leaving enough operating room after closing.
The company produces approximately $3.7M in revenue but only $280K in EBITDA.
That creates a clear operating thesis.
The opportunity is not primarily about finding more customers. It is about understanding where a large existing revenue base can produce better margins.
The buyer would take control of an existing service organization with staff, customers, and established systems.
The work becomes margin improvement, management, service quality, and resource allocation.
$1M Revenue · $204K EBITDA · 3.0x Multiple
An experienced services professional is pursuing an established automotive repair operation.
The buyer combines technical familiarity with operating experience.
That reduces the risk of entering an unfamiliar service environment while still creating an opportunity to apply stronger management and customer processes.
The proposed $610K acquisition is being structured through buyer equity, institutional financing, and seller participation.
GuildShore is supporting the opportunity analysis, diligence, financing, and transaction process.
The business reports approximately $204K in EBITDA on $1M of revenue.
At roughly 3.0x EBITDA, the valuation does not require aggressive growth assumptions to create a workable acquisition case.
The key question is how much cash remains after debt service and normal reinvestment in the shop.
The buyer would step into a functioning service center with technicians, customers, equipment, and operating history already in place.
The focus becomes bay utilization, technician productivity, customer retention, and pricing.
$1.1M Revenue · $330K EBITDA · 3.6x Multiple
A construction professional is pursuing an established renovation company rather than building one organically.
The buyer already understands the technical side of the work.
That means the ownership transition can focus on management, margins, sales, and team performance instead of learning the underlying service.
GuildShore is supporting the $1.2M acquisition through financing, seller-note negotiations, diligence, and coordination with legal and accounting advisers.
The central question is whether the business can comfortably support the proposed debt while maintaining enough liquidity to operate.
The company reports $330K in EBITDA on $1.1M of revenue, a reported margin around 30%.
At 3.6x EBITDA, the buyer does not need an aggressive growth assumption for the acquisition to make sense if the earnings normalize through diligence.
The buyer would spend less time performing technical work and more time managing the business around it.
The existing team allows ownership to focus on sales, margins, scheduling, and growth.
$1.2M Revenue · $335K EBITDA · 3.6x Multiple
An experienced transportation professional is pursuing the acquisition of an established freight operation.
The buyer already understands the operating realities of transportation.
That reduces the execution risk around scheduling, utilization, staffing, customer service, and asset management.
The proposed $1.2M share acquisition is being structured through multiple financing sources and seller participation.
The transaction does not rely on real estate value, so the underwriting is centered on the operating business and its ability to support the capital structure.
The company reports approximately $335K in EBITDA on $1.2M of revenue, a reported margin near 28%.
At 3.6x EBITDA, the economics can work well if normalized maintenance, fleet reinvestment, and customer concentration remain within acceptable levels.
The buyer would move from working inside the transportation industry to controlling the operating platform.
The focus becomes utilization, customer retention, fleet economics, and capital allocation.
$7.5M Revenue · $950K EBITDA · ~4.4x Multiple
A first-time acquirer with a background in multi-site operations and real estate is pursuing an established commercial landscaping company with a large recurring maintenance book.
The buyer previously managed regional operations for a multi-location service company and owns several investment properties.
He has approximately $500K of liquid capital and wants a business where his strengths in people management, route operations, budgeting, and local sales translate directly into ownership.
He is deliberately avoiding highly technical businesses where the seller is the primary source of expertise.
The company is being evaluated at approximately $4.2M, with roughly $7.5M in revenue and $950K in EBITDA.
The key diligence questions are maintenance-contract retention, crew productivity, customer concentration, equipment condition, route density, and how much revenue comes from recurring maintenance versus one-time project work.
The buyer would be acquiring an established customer base, crews, supervisors, equipment, and recurring maintenance contracts rather than trying to build route density from zero.
The recurring service base provides revenue visibility, while enhancement projects and additional services create upside within customers the company already serves.
The buyer would focus on branch performance, customer retention, crew utilization, pricing, and business development.
He would be stepping into an operating company with management infrastructure already in place, rather than becoming the person personally responsible for every job site.
$600K Revenue · $270K EBITDA · 3.7x Multiple
An experienced operator is pursuing a specialized industrial business with strong reported margins.
The buyer brings operating discipline and experience managing technical environments.
That matters in a niche business where customer relationships, technical knowledge, process consistency, and supplier relationships may represent much of the underlying value.
The proposed acquisition is being financed through buyer equity, institutional debt, and seller participation.
GuildShore is supporting diligence, financing, transaction terms, and legal coordination as the deal advances.
The company reports $270K in EBITDA on $600K of revenue, equivalent to a reported 45% EBITDA margin.
At roughly 3.7x EBITDA, the economics are compelling if those margins prove durable and transferable after the seller exits.
The buyer would inherit an established niche rather than attempt to create one.
The priorities become retaining technical capability, protecting key relationships, and growing without diluting the economics that made the acquisition attractive.
$800K Revenue · $570K EBITDA · 3.5x Multiple
An experienced operating professional is pursuing an established food business as a transition into ownership.
The buyer’s advantage is analytical and operational discipline.
The opportunity is not dependent on inventing a new concept. It is about understanding whether the current economics are durable and whether the existing operation can be improved under more structured management.
The proposed $2M acquisition is being structured through buyer equity, institutional financing, and seller participation.
GuildShore is supporting financial analysis, lender coordination, diligence, negotiation, and transaction execution.
The company reports $570K in EBITDA on $800K of revenue.
That is an unusually high margin, making normalization of earnings the most important diligence question in the transaction.
If the current EBITDA proves sustainable, an entry valuation of 3.5x creates substantial cash-flow capacity relative to the purchase price.
The buyer would inherit an operating team and established revenue base.
The job becomes protecting the economics, improving processes, and deciding where additional growth creates the best return.
$1.3M Revenue · $503K EBITDA · 3.5x Business Multiple
Two experienced operators are pursuing the acquisition of an established custom manufacturing business together with its real estate.
The buyers already understand construction, project execution, and operational management.
That reduces the learning curve around technical teams, production schedules, quality control, and customer delivery.
The proposed $3.3M acquisition includes both the operating company and the property.
The capital stack combines buyer equity, institutional financing, and seller participation, with GuildShore coordinating diligence and the legal and accounting work required to progress toward closing.
The company reports $503K in EBITDA on $1.3M of revenue, implying a reported EBITDA margin close to 39%.
That makes earnings verification especially important, but also explains the appeal of an entry valuation around 3.5x EBITDA.
The real estate provides an additional asset underneath the operating business.
The buyers would control both the production platform and the underlying property.
The focus becomes protecting the existing know-how while improving commercial execution, throughput, and capacity utilization.
$1.3M Revenue · ~$690K Adjusted Cash Flow · ~3.5x Multiple
A buyer is evaluating a specialized insurance-related consulting business with a remote, asset-light operating model.
This is fundamentally a people-and-relationships acquisition.
Unlike a fleet, facility, or manufacturing business, most of the enterprise value sits in technical expertise, client relationships, process knowledge, and the consultant network.
The company is being evaluated at approximately $2.4M, against roughly $1.3M in revenue and $690K in adjusted cash flow.
The transaction also contemplates a meaningful seller transition, because preserving client relationships and transferring technical knowledge are central to the value of the business.
The model generates substantial reported cash flow without requiring significant owned real estate, vehicles, or heavy equipment.
That creates an attractive capital-light profile.
The primary diligence issue is customer concentration. A small group of important relationships represents a meaningful share of revenue, so retention and transferability matter more than the multiple alone.
The buyer would inherit an established consulting platform, client base, billing infrastructure, and distributed professional network.
The opportunity is to reduce owner dependence and scale a model that already operates with relatively low fixed overhead.
$12M+ Revenue · $1.4M+ Adjusted Cash Flow · ~3.6x Multiple
A buyer is evaluating an established construction-services company serving complex residential and commercial projects.
This opportunity suits an operator who understands that a construction company’s real asset is not just its current backlog.
The harder assets to recreate are management depth, field execution, estimating discipline, subcontractor relationships, local reputation, and the ability to deliver difficult projects consistently.
The business is being evaluated at approximately $5M, with more than $12M in annual revenue and roughly $1.4M in adjusted cash flow.
The primary underwriting question is how much of that earnings base is institutional rather than tied to the seller’s personal relationships and oversight.
A buyer is not paying to assemble a construction company piece by piece.
The workforce, operating systems, project history, customer relationships, and market credibility already exist.
If those capabilities prove transferable, the buyer is acquiring an established execution platform at roughly 3.6x adjusted cash flow.
The buyer would step into a business already operating at eight figures of annual revenue.
The focus moves to project selection, margin discipline, leadership, capacity allocation, and controlled growth.
Target: $500K to $2M EBITDA per acquisition · Regional consolidation strategy
An established dental operator is pursuing a multi-acquisition strategy across adjacent markets, using existing practices as the building blocks for a larger regional platform.
This is not a first-time buyer learning the industry through acquisition.
The buyer already understands the clinical model, staffing requirements, patient economics, and operating constraints. That shifts the acquisition thesis from “Can we run this business?” to “Which practices become more valuable inside the group than they are on their own?”
The search is focused on profitable dental practices generating approximately $500K to $2M in EBITDA.
Each target is underwritten twice: first as a standalone business, then as part of the broader platform. The second analysis looks at geographic density, provider retention, patient mix, referral patterns, management depth, and which costs can realistically be centralized.
The goal is not simply to accumulate locations. It is to build a group where every acquisition improves the economics of the next one.
Independent dental practices often carry duplicate overhead across administration, recruiting, marketing, procurement, technology, and finance.
A well-executed roll-up can preserve the local clinical brand while consolidating selected back-office functions and increasing purchasing and recruiting leverage across a larger base.
The real value creation comes from combining existing EBITDA with operating leverage, rather than relying entirely on organic growth.
Each practice continues operating locally, but the group becomes increasingly centralized where scale creates an advantage.
Over time, the buyer shifts from owning individual practices to allocating capital across a regional healthcare platform.
$7M Revenue · $730K EBITDA · 3.3x Business Multiple
Two first-time buyers are pursuing an established powersports retailer together with the real estate supporting the operation.
The buyers bring operating and management experience, but are new to business ownership.
That makes the quality of the existing platform important. The acquisition already has the employees, customers, technical capability, physical infrastructure, and operating history that would otherwise take years to assemble.
$2.4M operating business $2.8M real estate
GuildShore is coordinating financing, seller participation, diligence, negotiations, and the closing process across both components.
The operating business reports $7M in revenue and $730K in EBITDA, implying an entry multiple of roughly 3.3x EBITDA.
The buyers are pursuing two assets through one transaction: the earnings of the business and the property that supports those earnings.
That creates a different ownership profile from buying the operating company alone.
The buyers would inherit an established team, customer base, service operation, and property.
Their role becomes improving an existing platform rather than building one from zero.